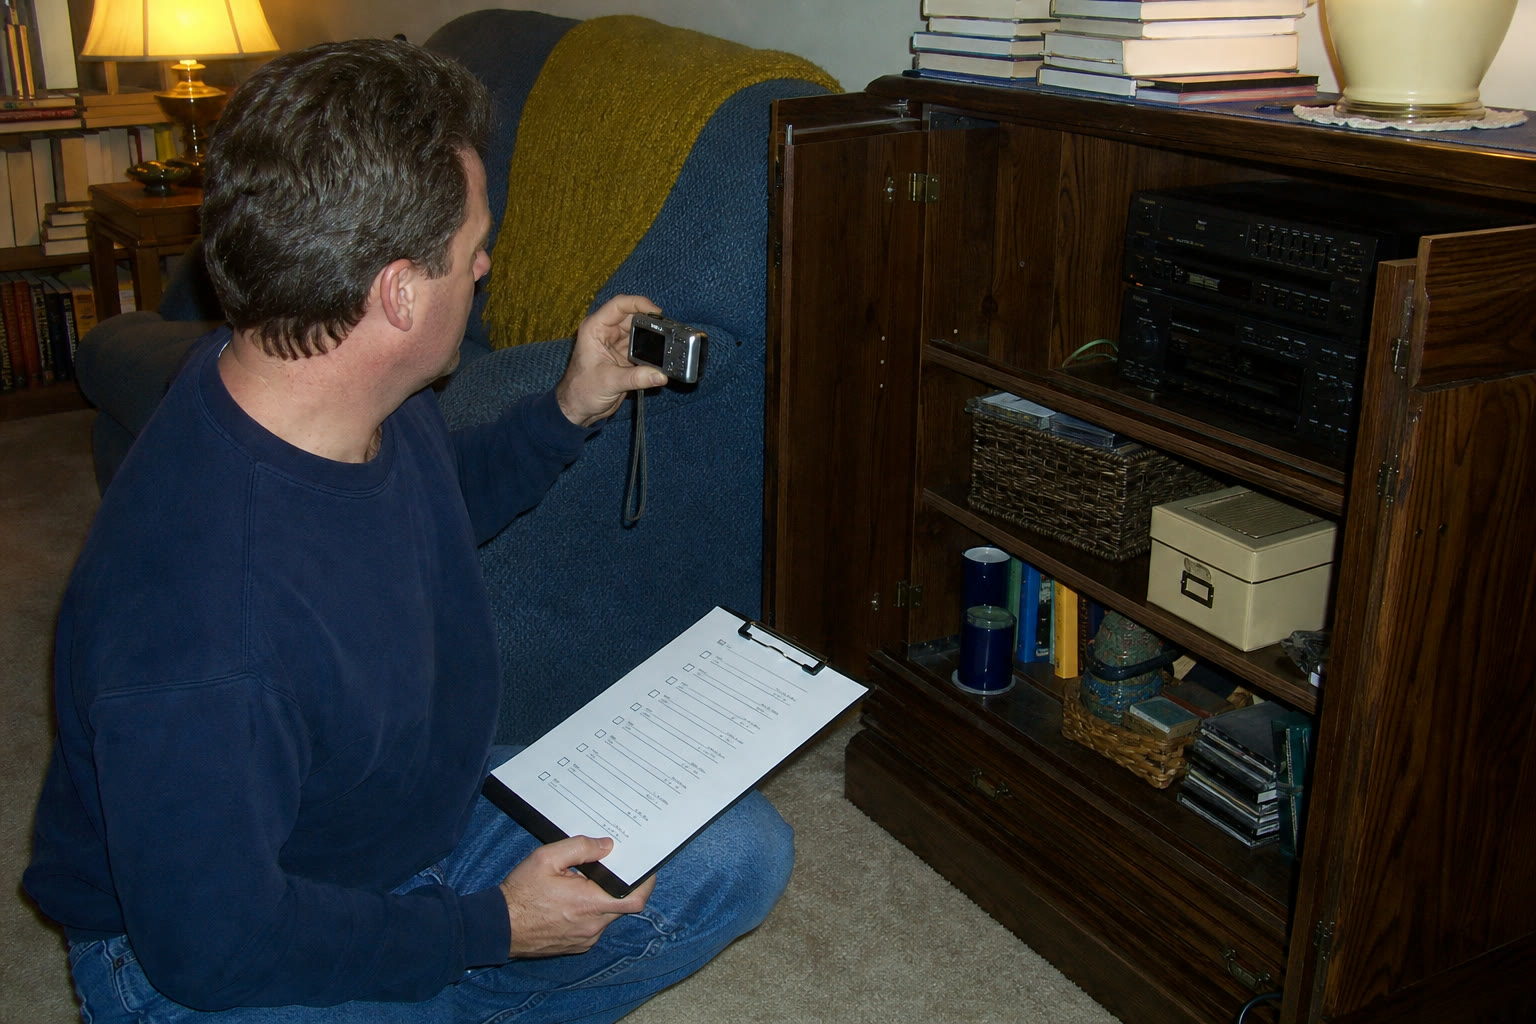
After a theft, fire, or storm, nobody remembers the brand, age, and rough value of every coat, pan, tool, and lamp. An inventory gives the claim a starting record.
Start with a slow room video
Stand at the doorway. Say the room name and date. Move slowly. Open closets, cabinets, and drawers. Name useful details out loud: “six dining chairs,” “winter coats,” “cordless drill,” “set of pans.” Do not film private papers, medicine labels, passwords, or keys.
Take close photos of the expensive or odd things
Photograph model and serial labels on appliances, electronics, tools, bikes, and equipment. Photograph jewelry, art, collections, and special items from more than one angle. Those items may have policy sublimits and may need separate scheduled coverage.
Add proof when it is easy
Receipts, order emails, appraisals, manuals, and old photos can help. Do not stop the whole project because a receipt is gone. A decent inventory now is better than a perfect inventory never.
Pal rule: finish the first rough video today. Make it pretty some other year.
Store it somewhere else
A list kept only in the house can disappear with the house. Keep an encrypted cloud copy, a secure drive in another location, or another safe backup. Protect the account with a strong unique password and multi-factor authentication.
Do not publish your stuff
A home inventory is a map of what you own. Do not post it publicly. Do not email it to My Rate Pal. Share it with an insurer or adjuster only through the secure method it provides when a claim or coverage review needs it.
Use the inventory to check the policy
Add a rough replacement total by room. Ask the agent how the personal-property limit and settlement method work. Ask about sublimits for cash, jewelry, firearms, business property, collections, electronics, and other listed categories.
Update after the obvious days
Do a quick update after holidays, a move, a renovation, or a large purchase. Put one recurring reminder on the calendar. Ten fresh minutes is enough.
An inventory does not guarantee a claim payment. Coverage, cause of loss, limits, deductibles, proof, and policy terms still decide the claim.
Where we checked
Go straight to the source
- NAIC Home InventoryRegulator tips and inventory tools for documenting belongings.
- NAIC home insurance guidePersonal-property coverage, limits, and claim basics.
We link to the official office when one exists. A link is not an endorsement, and we do not control outside sites.